The Deal Everyone Loves
Data center flexibility is basically Hansel from Zoolander- so hot right now. There’s a ton of conversation about how DC flexibility could be the solution everyone has been hungry for. If they could flex down when the grid needs them to, data centers could be the ultimate grid asset vs a liability. If designed well, that flexibility could improve utilization of existing grid infrastructure and potentially reduce system costs for other customers. Whether those savings actually flow through to lower retail rates is still very much up for debate. Utilities get more revenue without building new wires, the numerator increases while the denominator stays the same. There’s apparently ~100 gigawatts of untapped capacity if we just used the existing infrastructure smarter.
And there are some really cool startups raising a lot of money on this: GridCARE just raised a Series A and announced a successful proof point with PGE finding some excess capacity on their wires with software. Verse just raised a bunch of money promising speed to power and solutions to help grid flexibility with behind-the-meter solutions. People are using AI itself to find more capacity to build more AI which is kind of like AI advocating for building itself. Emerald AI is another one doing some really cool work on flexibility and also just raised a bunch of money. Google has been a leader in the space. LōD is doing something really cool with Dominion. More on them later.
And honestly, data centers and AI could use some positive press right now, because everywhere you look, there’s a new article about irreversible price increases due to data center load growth, and now there are protests all across the country against data centers. It’s a real problem!
Altruism vs Economics
Offering grid flexibility sounds great on paper, but it hasn’t been actually done at scale yet. We’re still in the early innings, so nobody is to blame, but I also think it’s important to note that data centers actually don’t want to be flexible from a raw economics perspective. Why would they? They’re making money hand over fist converting electricity into one of the most lucrative products: intelligence. So data centers won’t do this unless the benefits of providing flexibility outweigh the lost revenue.
DC flexibility is all well and good and should be done wherever possible. And if you’re vertically integrated like Google or others, it’s fine to offer flexibility in exchange for favorable interconnection terms. They’ve been doing it for years, even before the AI boom, flexing workloads around to manage carbon emissions. But if you’re not vertically integrated, there are some real challenges associated with offering deep levels of flexibility to the grid.
For example, for co-located data centers, they have Service Level Agreements (SLAs) that require high uptime. So they don’t even control the workloads voluntarily themselves, the tenant does. And there are many other leasing structures that similarly don’t allow for voluntary economic curtailment, which is what we’re talking about in the flexibility conversation. So ultimately, the utility interconnection agreement needs to actually reach into and be cohesive with the end use agreement with the customer. And the only way to make that happen at scale, is if everyone understands the economics and the tradeoffs.
How Measuring Leads to Scale
Only when the specific economics of flexibility are adequately understood by all sides can there be a scalable deployment in contracts. Otherwise, while it sounds nice in the press, you won’t see adoption at scale. So what really needs to get measured accurately is the economics between the interconnection agreement and the end product. Or the economics of electrons converting into compute. Electricity into tokens.
That’s exactly what the Compute Heat Rate (CHR) measures. Different data center workloads have different electricity price tolerance thresholds, or different CHR levels. For example, frontier inference has a CHR of over $74,000/MWh, meaning it would make no economic sense for a data center to offer direct workload curtailment for frontier inference loads at any price the grid can possibly produce. Mid-tier inference, including for example the recent Kimi K3 model, comes out at about $5,000/MWh CHR. Commodity inference or “freemium” inference around $500/MWh.
Workload classification is therefore a prerequisite for credible flexibility. A megawatt of batch inference and a megawatt of frontier interactive inference may look identical to the grid, but economically and operationally they are completely different products.
So understanding this first is key: if you or your tenant is running a mix of workloads, you may be comfortable offering some flexibility on low-CHR workloads, if the electricity price increases above that threshold.
How Measurement Translates to Deals
Depending on what side of the negotiation you’re on, understanding relative CHR values for workload tiers is critical to finding a deal that works. For the utility or ISO, if you understand the order of magnitude of lost revenue during curtailed hours, you can appropriately size flexibility offers that data centers can actually agree to. Let’s use a concrete example.
Take a 100 MW facility that signs a flexible interconnection agreement with 40 curtailment hours a year. That’s squarely in the range the Duke Nicholas Institute study assumed, 0.25% to 1% of hours, to unlock the 76-126 GW of headroom everyone keeps quoting. Forty hours sounds like nothing. But if those hours are met through direct workload curtailment, 100 MW times 40 hours times a blended CHR of $6,000 is $24 million per year in forfeited compute value- and that’s only for 40 hours! Manageable, but not nothing. That number should be sitting in the term sheet right next to the interconnection discount.
And that’s obviously on the very low end of flexibility- given how data centers are densely concentrated in specific areas, flexibility needs to scale similar to Google’s offered levels, like 10% of the DC capacity, and then the numbers start looking very material.
The Levers of Flexibility
There’s an important nuance here: flexibility does not necessarily mean shutting servers off or turning things down. There are multiple ways a data center can reduce its impact on the grid, and they have very different economics. Some are SLA-safe, meaning the end customer may never know anything happened, or may not have their service negatively impacted by the actions taken. Others actually defer, degrade, or interrupt the underlying compute. Generally, the more valuable and time-sensitive the workload, the more expensive it becomes to use flexibility mechanisms that interfere with the compute itself for obvious reasons.
Once that classification exists, the question becomes which flexibility mechanism fits each workload. Before a data center can credibly promise 10%, 20%, or 30% flexibility to a utility, it needs to know which workloads behind that meter can move in time or geography, which have contractual uptime requirements, and what economic value is lost if they are interrupted.
There is a ladder of flexibility options. At the low-cost end, low CHR or delay-tolerant compute can simply be curtailed or deferred. Higher CHR workloads might be throttled rather than stopped. Others can potentially be shifted geographically to another data center. When the compute’s CHR is too valuable, latency-sensitive, or contractually protected to interrupt at all, the flexibility can move from the compute side to the power side: keep the servers running, but temporarily reduce their demand on the grid using onsite generation, storage, or another source of power.
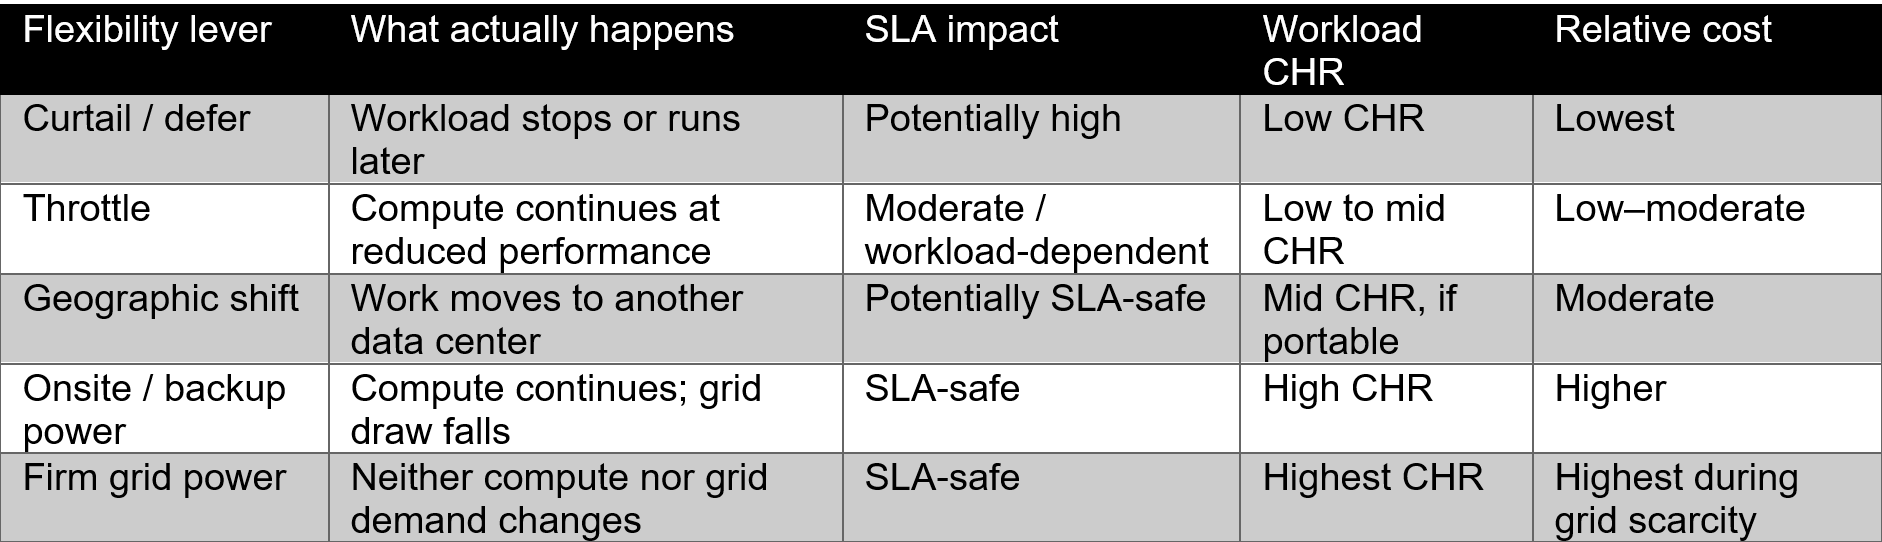
Emerging frameworks such as Grid 2.0 are beginning to explore differentiated tiers of grid service for flexible loads. The next question is how those service tiers map to the very different economic values of the workloads consuming that electricity.
This is where the CHR becomes more useful than simply identifying a “curtailment price.” CHR provides an economic classification of the workload, and that classification can help determine which flexibility lever makes sense in the first place. A $500/MWh workload and a $74,000/MWh workload should not be offered the same flexibility product, even if they happen to sit in identical buildings.
The real-world implementation therefore starts to look something like this:
Classify the workload → measure its CHR → identify the SLA-safe flexibility options → determine the lowest-cost viable lever → contract that capability with the utility or grid operator.
And we’re beginning to see versions of that last step emerge in the real world.
ERock is pursuing a power-side version of flexibility: rather than requiring valuable compute to stop, onsite generation can allow the data center to keep operating while temporarily reducing its demand from the grid.
Its El Paso project is a particularly interesting example. ERock and El Paso Electric are partnering to provide 366 MW of onsite generating capacity for Meta’s data center campus during an up to five-year bridge period, with Meta funding the generation. ERock generation will provide power to the campus while the infrastructure needed for permanent grid service is completed. Once that infrastructure is in place, the generation can support the broader El Paso Electric system grid reliability. In other words, the asset that delivers speed to power during the bridge period can become a permanent grid resource.
That is the utility’s framing. The broader project has raised concerns in El Paso about who ultimately bears the cost of flexibility. In that context, the ability to deploy generation that can serve the customer during the bridge period and support the grid over the longer term illustrates how onsite generation can help address growing power demand while providing flexibility value beyond a single customer.
That’s a fundamentally different form of flexibility from shutting off inference. The compute can remain available to the customer while the electricity supply itself becomes flexible.
We are still in the early innings of figuring out which mechanisms work best, for which workloads, and at what price. But the direction is becoming clearer: there probably isn’t one price of flexibility. There is a cost curve. And where a workload sits on that curve should depend, at least in part, on its economic value.
Mapping these flexibility levers directly against CHR workload tiers is the next step in this research, so stay tuned on that!
The Trade Both Sides Actually Want
So how does this actually get negotiated? Strip away the grid-citizenship framing and a flexible interconnection agreement is just business development. The utility is selling the scarcest product in the market right now, speed to power. The developer is selling an option, the utility’s right to call curtailment. Both sides should price what they’re selling. For the utility or ISO, that means sizing the ask to the tenant’s workload mix, because an offer calibrated to low-CHR workloads gets signed, while an offer that reaches into frontier territory gets lawyered to death. For the developer, the CHR math above is the walk-away number: price the curtailment option at forfeited compute value, not at whatever the local demand response program happens to pay.
And that’s why the trade both sides ultimately want to make is flexibility for speed to power. The same CHR math that makes curtailment expensive makes early energization enormously valuable: a 100 MW facility that gets to market a year sooner spends that year converting electrons into revenue at full CHR economics. Give up 40 hours a year to gain a year? In most scenarios that trade isn’t close. Which is exactly why utilities holding scarce interconnection capacity suddenly have real leverage, and why developers should be lining up to make this trade everywhere it’s on offer.
The Live Experiment
Most of the flexibility conversation, this piece included, is still at the whitepaper stage. At least one company is already running the experiment. LōD Technologies, founded by Medi Naseri, was selected into Dominion Energy Innovation Center’s 2026 Accelerate cohort, and their CLōD platform reprices AI inference against real-time electricity prices and grid conditions. In plain terms: instead of asking data centers to promise flexibility in a contract, it puts a live price on flexibility and lets workloads accept or decline it in real time. Nobody has to pledge anything. The price does the negotiating.
The team cut their teeth orchestrating flexibility at industrial scale in bitcoin mining before pivoting to AI inference, which puts them in the rare position of having actually dispatched flexibility at scale rather than just modeled it. That is exactly the execution layer the measurement argument in this piece has been calling for. CHR gives every workload tier a price tolerance on paper. A platform like CLōD is where those tolerances meet an actual price in the real world.
So let me close with a falsifiable prediction: when price-based flexibility platforms like this start generating real data, the flexibility supply will concentrate in the batch and commodity inference tiers, and the frontier interactive share will barely move, because that’s what the CHR tier math says has to happen. I’m happy to be graded on that one. Revealed-preference data from platforms like LōD’s is the first market instrument capable of doing the grading. We’ll see!
Measurement Before Matchmaking
None of this is an argument against flexible interconnection. It’s an argument for pricing it like the deal it is, and the demand side finally has the number to do it. CHR is that number: the framework is in the CHR paper on SSRN, and the quarterly reference values live at computeheatrate.com. The next question is the one I’m working on now: what’s the actual exchange rate between flexibility and speed to power, how many curtailment hours buy how many months of earlier energization? That’s forthcoming research, and the early math suggests the answer will surprise both sides of the table. If you’re negotiating one of these agreements in the meantime and want to run the numbers on your specific deal, you know where to find me.
More soon.
Great work, Hans.